 Mariama Hamani
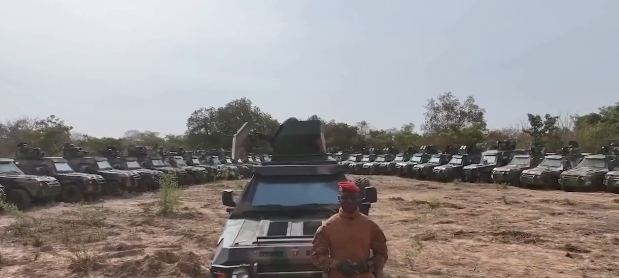
A narrative of reclaimed destiny
Since Captain Ibrahim Traoré took power, official communication has gradually settled on a single, powerful storyline: that Burkina Faso has retaken control of its own fate, curbed its reliance on outside actors, and chosen to finance its war against armed groups from its own pocket.
Politically, the message works. Rearmament is presented as the tangible proof of sovereignty. Military acquisitions are highlighted, the patriotic support fund is held up as the expression of a national effort, and calls for citizens to contribute are used to demonstrate that the country intends to count first and foremost on its own resources.
One question, however, is far less ideological and remains largely unanswered: what does this sovereignty actually cost, and who ultimately foots the bill?
The changing scale of defence spending
Budget documents already make the shift in magnitude plain.
Spending on defence and security, which hovered around 95 billion CFA francs in 2016, has climbed into the hundreds of billions and, depending on the budgetary perimeter used, exceeded 800 billion in 2024.
The trajectory is considerable, and it reflects an unambiguous political priority: in a country facing a major security crisis, the state now devotes a far larger share of its resources to the army, the security forces, equipment and the war effort.
Yet a rise of this magnitude cannot be read purely through a military lens. Every additional billion directed to security is also a billion that has to be found somewhere — and it is precisely at that point that the sovereignty narrative meets the machinery of public finance.
What the patriotic fund does — and does not — cover
The patriotic support fund stands among the most visible symbols of the strategy.
Contributions have reached substantial sums since it was created: close to 99 billion CFA francs in its first year, roughly 175 billion in 2024, and more than 200 billion according to the figures released for 2025.
It would be unfair to dismiss the scale of that national mobilisation. But another illusion deserves scrutiny: the fund alone does not represent the entire financing of the war effort.
The state budget remains the principal vehicle for public policy. Military expenditure is therefore also fed by tax revenue and ordinary state resources and, whenever those fall short, by recourse to borrowing.
In other words, contributing voluntarily to the war effort does not mean the war is being financed without debt.
Debt that merely changes hands
This is where the discussion becomes more instructive.
Burkina Faso’s public debt has risen sharply since 2021 and now exceeds 8,000 billion CFA francs, based on the data and projections available for recent years.
A significant portion is now raised on the regional WAEMU market, notably through the issuance of public securities.
This allows the country to diversify its funding sources and to reduce certain dependencies on external creditors. But debt contracted on the regional market is still debt.
Whether it is held by a bank, an institutional investor or another financial player in the region, its economic nature does not change: the state borrows today and must repay tomorrow, with interest.
Here the sovereignty messaging reaches its limits. One can perfectly well defend the choice to prioritise domestic financing, and one can consider borrowing from the regional market preferable to certain forms of external dependence. Presenting that mechanism as the disappearance of financial dependence, however, would be misleading.
The quieter burden of debt service
A less spectacular but far more durable risk also exists: the cost of servicing the debt.
Every loan taken out today creates an obligation for the years ahead. When interest rates are high and investment needs remain substantial, the government must set aside more resources to meet its repayment schedule.
The mechanism is simple: the more the state borrows, the more of its future revenue it must reserve for its creditors.
Indebtedness in itself is not necessarily the problem — all modern states borrow. The real question is whether the spending financed by debt generates enough economic and social returns for the country to carry the future burden.
For military spending, the equation is trickier still: equipment may be indispensable to national security, but it does not automatically generate the revenue needed to repay the loan that financed it.
The trade-offs that speeches rarely show
The central issue is not whether Burkina Faso has the right to rearm. It clearly does.
The issue is establishing what that rearmament costs the public finances as a whole.
When a growing share of resources is channelled towards security, the government must arbitrate between competing priorities: defence, education, health, infrastructure, agriculture, social protection and debt repayment.
Such arbitrations are seldom visible in political speeches. Yet they constitute the true test of economic sovereignty.
A state can buy more weapons and remain financially vulnerable. It can scale back certain foreign military partnerships while increasing its reliance on borrowing. It can mobilise patriotic contributions while committing a growing share of its future revenue to servicing debt.
A diplomatic rupture, in short, does not automatically amount to a financial rupture.
Military autonomy, economic dependence
This is the contradiction the Burkinabè model lays bare.
The authorities claim strategic autonomy: new partners, a diversification of alliances, national mobilisation and a reduction of certain traditional partnerships.
At the same time, the economy continues to run on the classic instruments of public financing — taxation, domestic debt, the regional market, multilateral creditors and economic cooperation.
There is nothing exceptional about that. It is how any state with limited resources and considerable security needs functions.
The difficulty begins when political communication turns that financial reality into a story of absolute self-sufficiency.
Separating credible figures from inflated ones
Some claims circulating on social networks also need to be put back in order.
Talk of a military debt of “hundreds of billions of dollars” is incompatible with the size of Burkina Faso’s economy.
The country’s GDP falls within a range of a few tens of billions of dollars, not hundreds of billions. A military debt of several hundred billion dollars would vastly exceed its economic capacity.
The reality is already substantial enough not to require exaggeration. What is at stake is hundreds of billions of CFA francs, not hundreds of billions of dollars — a distinction that matters for any serious analysis.
The expense behind the slogan
Burkina Faso can therefore legitimately claim political and military sovereignty while remaining an indebted state.
That reality, however, forces a more demanding question: how far can the financing of the war go without weakening the state’s other functions?
Sovereignty is not measured solely by the number of armoured vehicles, drones or weapons acquired. It is also measured by the capacity to pay civil servants, invest in education and health, fund infrastructure, support the productive economy and, above all, repay the loans taken out in the name of the collective.
The point is not to deny the efforts made by the Burkinabè authorities. It is to look behind the narrative.
- Who pays?
- How much?
- With which resources?
- And for how long?
If a substantial part of the rearmament rests on public revenue, national contributions and borrowing, then the proclaimed sovereignty is not a sovereignty without cost.
It is a sovereignty financed by taxpayers, savers, financial markets and future generations.
That is precisely why the expression “sovereignty on credit” deserves to be posed as a question rather than repeated as a slogan.
Political independence can be declared in a handful of speeches. Financial independence, by contrast, is verified in the accounts.

 Boureima Amadou