 Boureima Amadou
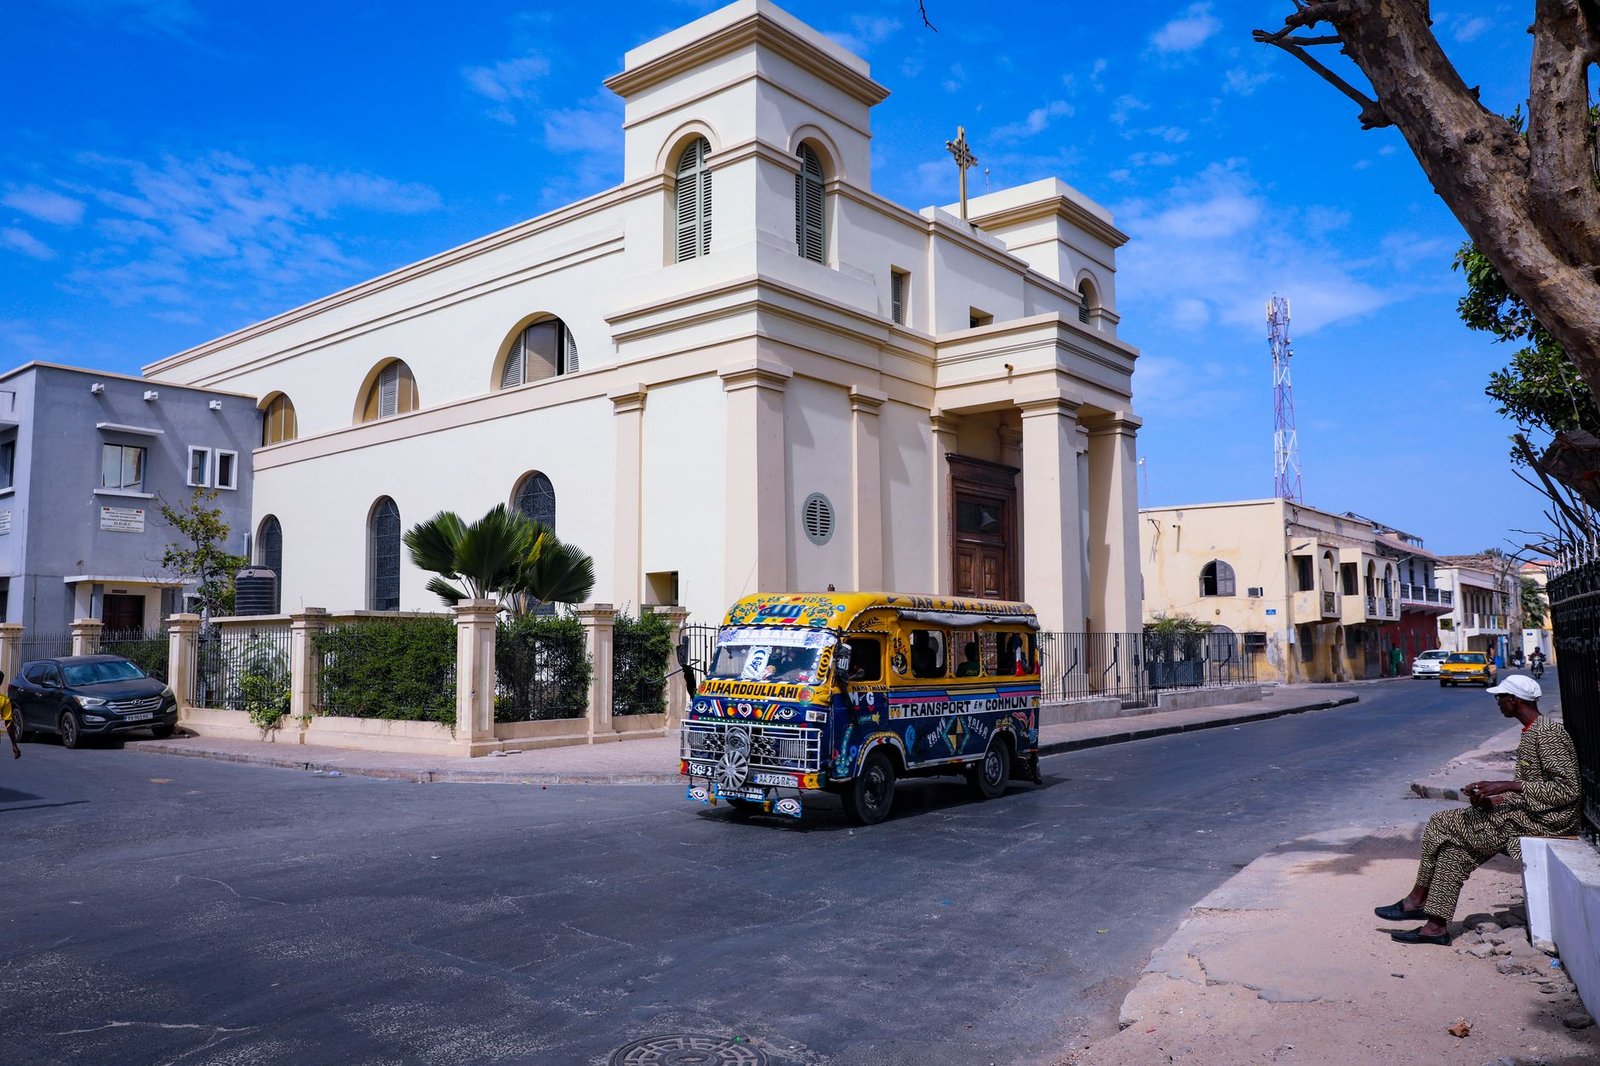
The warning shot fired by Ousmane Sonko from the floor of Senegal’s National Assembly sent shockwaves through the dollar-bond market on Monday. As president of the National Assembly and leader of the ruling Pastef party, Sonko threatened to withhold approval for both the 2026 mid-year finance law and the 2027 draft budget. Secondary-market quotes show the country’s sovereign dollar bonds suffering their steepest weekly decline since early September.
Paradoxical rebellion rattles investor confidence
A defining twist in the crisis is that the challenge to fiscal consolidation does not come from the opposition benches but from within the presidential majority itself. Pastef holds a commanding majority after the November 2024 snap elections, giving Sonko’s parliamentary veto immediate clout over President Bassirou Diomaye Faye’s ability to push through planned spending cuts.
Sonko zeroed in on 555 billion CFA francs of proposed reductions in capital expenditures earmarked for the ministries of National Education, Family & Social Solidarity and Vocational Training—key pillars of Senegal’s social contract. Equally contentious is the envisaged phase-out of fuel, electricity and bread subsidies, a politically incendiary issue in a country where basic commodity prices remain a barometer of public sentiment.
“Major cuts to the education budget, family support and vocational training cannot be justified,” Sonko told national media. He also rejected the underlying adjustment framework, linking it directly to the ongoing negotiations with the International Monetary Fund.
IMF programme and G20 Common Framework put on the line
Since 2024, when the previous administration was found to have underreported public debt, Dakar has been locked in parallel talks with the IMF and negotiating a debt reprofiling under the G20 Common Framework launched in 2020. An agreement at the IMF staff level has been reached, clearing the way for board consideration and subsequent disbursements—but every step hinges on parliamentary endorsement of a credible budget path.
Sonko framed his objection in nationalist terms. “We cannot simply follow the IMF’s or any other creditor’s wish list,” he said. “Senegal should not be the Guinea pig for the G20’s latest initiative.” He questioned the legality of the debt being restructured, arguing it was contracted without parliamentary ratification.
The stand-off creates twin headwinds: it pushes up the political-risk premium on Senegal’s eurobonds after weeks of relative calm, and it risks delaying the release of concessional financing at a time when heavy debt-service obligations and ballooning post-2025 spending tied to the Grand Tortue Ahmeyim gas project loom large.
Street protests add fuel to the political fire
Parliamentary gridlock is now colliding with mounting street pressure. Trade unions have called for a three-day general strike starting 21 October, targeting the public sector and parts of the formal economy. The convergence of parliamentary resistance and social unrest underscores the fragility of President Faye’s political position, especially when his own party is no longer united behind unpopular fiscal measures.
Sonko sought to cast the Assembly as the pragmatic party. “We are not here to obstruct; if there is a stalemate, the responsibility lies squarely with the executive,” he told reporters. The statement, while couched in conciliatory language, leaves open the prospect of an extended tug-of-war between the presidency and the speaker’s office—a scenario most investors had not priced into their models for West African sovereign debt.

 Mariama Hamani