 Mariama Hamani
The rising burden on citizens and enterprises
Burkina Faso’s public debt has climbed sharply in recent years, and the consequences are being felt far beyond government ledgers. As the state borrows more, the pressure on public finances intensifies, with direct implications for households, businesses, and the broader economy. The gap between the official narrative of financial sovereignty and the mounting debt stock raises urgent questions about who ultimately bears the cost.
From 4,765 billion to over 8,700 billion FCFA: a rapid escalation
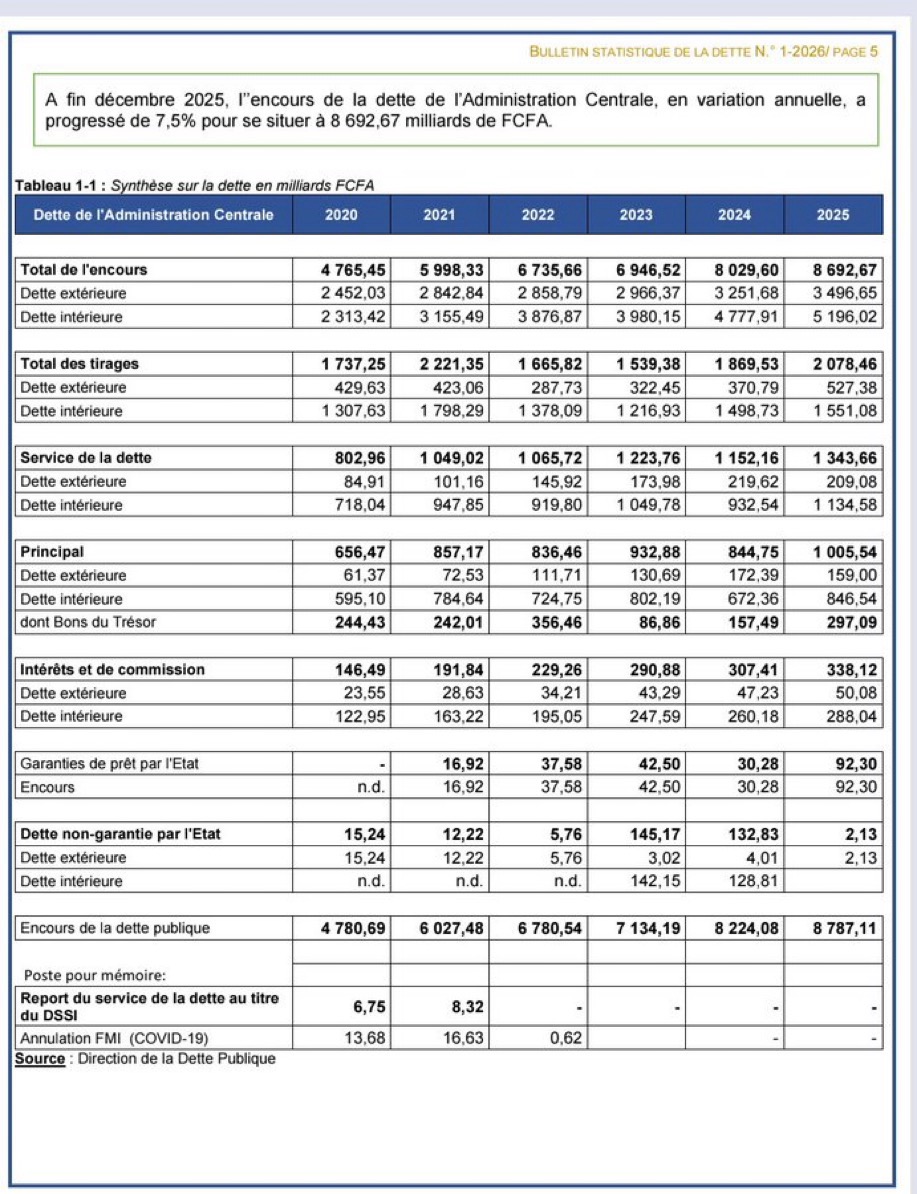
At the end of December 2020, the outstanding debt of the central administration stood at 4,765.45 billion FCFA. By the end of 2021, it had already reached approximately 6,107 billion FCFA, according to data from the Ministry of Economy and Finance. The upward trend continued unabated. The latest available statistical bulletin from the Burkinabè Treasury indicates that the central administration’s debt stock reached 8,692.67 billion FCFA at the end of December 2025. Just a few months later, by the end of March 2026, it had risen to 8,731.5 billion FCFA. In essence, within a few years, Burkina Faso moved from a debt level below 5,000 billion FCFA at the end of 2020 to more than 8,700 billion in 2026.
What the borrowed funds are used for and at what cost
The critical issue is not whether a state borrows, but why and on what terms. Public debt is not inherently a sign of mismanagement. Governments may borrow to finance infrastructure, support investment, address security crises, or maintain public spending when revenues fall short. The essential questions are: what are the new loans used for, at what cost are they contracted, and what future repayment capacity do they generate? The structure of Burkina Faso’s debt warrants close attention. At the end of 2025, nearly 60% of central administration debt was domestic, primarily in the form of Treasury bills and bonds. Domestic debt alone amounted to approximately 5,196 billion FCFA. This shift matters because domestic financing is not free. Principal must be repaid, and interest payments add to the burden. In the first quarter of 2026, debt service already reached 407.1 billion FCFA, up 31.5% year-on-year, according to Treasury data.
The price of financial sovereignty
Ibrahim Traoré can legitimately advocate for economic sovereignty. However, sovereignty is not measured solely by refusing certain partners or making declarations of financial independence. It is also measured by a state’s ability to sustainably increase revenues, control spending, finance investments, and contain the weight of debt service. Burkina Faso possesses significant mining resources, particularly gold. Yet the existence of these resources does not automatically mean the state has enough liquidity to fund all its ambitions without borrowing. The real debate should shift: the challenge is not to proclaim that Burkina Faso will not borrow, but to demonstrate that every franc borrowed generates sufficient value to justify its cost.
Implications for the economy and the population
The government can highlight its investments, military efforts, infrastructure, or social policies. But these expenditures must be weighed against the evolution of debt. The International Monetary Fund, in its 2026 analysis, classifies Burkina Faso at moderate risk of debt distress, while considering the debt sustainable in the medium term. The institution nevertheless points to several vulnerabilities, including refinancing risks associated with domestic debt, dependence on gold export revenues, and the security situation. It would be excessive to present this debt increase as mechanical proof of insolvency; available data do not support such a conclusion. Yet it would be equally difficult to argue that the country has developed in recent years without significant recourse to borrowing. The figures tell a different story.
The unanswered questions
Between the end of 2020 and the first quarter of 2026, the central administration’s debt stock increased by nearly 4,000 billion FCFA. The remaining question is simple but politically and economically momentous: if Burkina Faso does not need to borrow to build itself, how can the public debt have risen by several thousand billion FCFA during this period? This apparent contradiction between the discourse of financial sovereignty and the evolution of public accounts demands precise answers from Ibrahim Traoré’s government: how much was borrowed, from whom, at what rate, to finance which projects, and with what measurable results for the population? In public finance, slogans may appeal, but the numbers remain to be explained—and their consequences for citizens and businesses are already unfolding.
By Boureima Amadou — Reporter

 Boureima Amadou